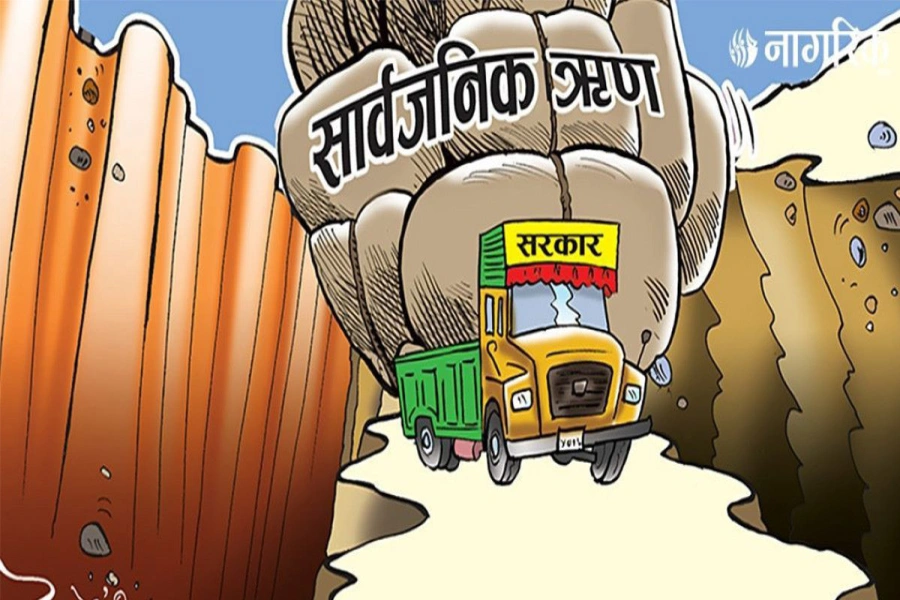
KATHMANDU, Nov 17: Banks in Nepal are awash with cash, but businesses remain reluctant to expand investment. Weak credit demand has left banks and financial institutions with excess liquidity of nearly Rs 800 billion, reflecting sluggish investment and borrowing activity in the economy.
According to Nepal Rastra Bank (NRB), deposits in banks and financial institutions reached Rs 8.532 trillion as of November 4 (Kartik 18). However, lending has failed to keep pace with deposit growth. Banks and financial institutions had extended loans worth Rs 6.111 trillion, leaving excess liquidity of Rs 783 billion.
Excess liquidity refers to funds available to banks beyond what they need for lending and other financial transactions. It builds up when deposits grow faster than demand for loans.
Anil Sharma, chief executive of the Nepal Bankers' Association, said weak economic activity has prevented credit growth despite historically low interest rates.
"Credit expansion has remained sluggish because economic activities have not picked up. Investment has failed to increase even though loans are available at low interest rates," Sharma said.
He said banks and the central bank were trying to identify why investment remained weak despite the presence of a stable government. "Banks and NRB are looking for answers, but the reasons have yet to be established," he said.
Interest rates have continued to fall. The average maximum interest rate on individual fixed deposits at commercial banks dropped below 4 percent to 3.92 percent for Mangsir, compared with 4.013 percent in Kartik. Borrowers can also access loans at single digit interest rates.
Lending slows as banks focus on recovery of loans at fiscal yea...
The main reason for excess liquidity is the widening gap between deposit growth and credit expansion. Rising remittance inflows and improved foreign exchange reserves have increased deposits in the banking system. However, demand for loans from the private sector, industries and new projects has remained below expectations.
Businesses have shown limited interest in establishing new industries, expanding existing operations or investing in large projects. Uncertainty over the investment climate, weak business confidence, subdued market demand and slow economic activity have also affected borrowing.
Anjan Shrestha, president of the Federation of Nepalese Chambers of Commerce and Industry (FNCCI), said businesses were adopting a wait and watch approach because problems that emerged during the Covid pandemic remained unresolved.
He attributed weak market demand to the pandemic, the Gen Z protests, natural disasters at different times and the government's limited spending capacity.
"One problem after another has disrupted the market cycle. Existing industries cannot operate at full capacity because demand has not increased. No new industries are opening, and investment expansion has consequently stalled," Shrestha said.
He added that attacks on private businesses during the Gen Z protests had further weakened business confidence. However, he expressed optimism that policy reforms under the new stable government could improve the private sector's confidence. According to him, the government has amended 59 laws in an effort to restore that confidence.
Weak government spending has also contributed to the liquidity buildup. When revenue collection exceeds government expenditure, money accumulates in government accounts instead of circulating through the economy.
Low capital expenditure limits the flow of funds to the private sector and the market. It also slows construction, industrial production, supply chains and employment generation.
Deposits and lending edge up
NRB data show that deposits and lending both recorded modest daily increases as of November 4.
Commercial banks held deposits worth Rs 7.715 trillion, up Rs 7 billion from Rs 7.708 trillion a day earlier. Other banks and financial institutions held Rs 817 billion, slightly down from Rs 818 billion.
Total deposits across the banking system reached Rs 8.532 trillion.
Total lending stood at Rs 6.118 trillion, up Rs 4 billion from Rs 6.114 trillion the previous day. Commercial banks accounted for Rs 5.438 trillion of the total, an increase of Rs 3 billion. Lending by other banks and financial institutions remained unchanged at Rs 680 billion.
The slower growth in lending compared with deposits has pushed down the credit to deposit (CD) ratio. NRB reported the ratio at 70.96 percent as of Kartik 18, indicating that banks have considerable room to expand lending.
Six banks cut interest rates
Six commercial banks reduced deposit interest rates for Mangsir, while 14 retained their Kartik rates. None increased rates.
According to the new rates published by all 20 commercial banks, the average maximum interest rate on individual fixed deposits fell by 0.11 percentage points, from 4.013 percent in Kartik to 3.92 percent in Mangsir.
The average maximum rate on institutional deposits also declined from 3.003 percent to 2.9905 percent.
Machhapuchchhre Bank made the steepest cut, reducing its individual deposit rate by one percentage point, from 4.5 percent to 3.5 percent. Agricultural Development Bank cut its rate by 0.5 percentage points to 3.65 percent.
NMB Bank reduced rates on both individual and institutional deposits by 0.25 percentage points. Laxmi Sunrise Bank, Kumari Bank and Standard Chartered Bank also lowered rates on individual deposits.
With banks continuing to reduce deposit rates, returns for fixed deposit holders are likely to decline further.